Here is an original news-style rewrite of the supplied material, with the analysis and recommendations attributed to The Nigerian Insurers Association (NIA) has urged insurance companies to strengthen their core underwriting operations as the recent reduction in interest rates could reduce the extent to which investment income supports weak underwriting performance.
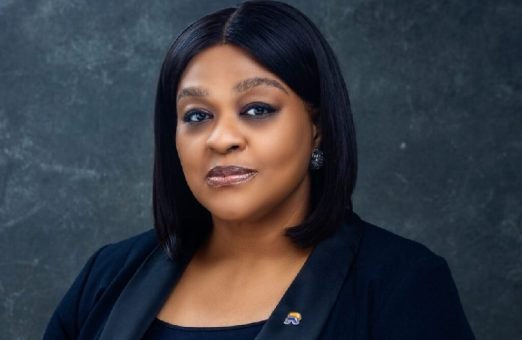
NIA Chairman, Mrs Ebele Nwachukwu, said the lower-interest-rate environment presented both challenges and opportunities for insurers, particularly if cheaper credit eventually stimulates broader economic activity.
Nwachukwu, who is also the Managing Director of Rex Insurance, said the impact of the rate cut would vary across different segments of the insurance industry because insurers have different liability structures and investment horizons.
She explained that general insurance companies could experience the effect of declining yields relatively quickly because their liabilities are largely short-term and investments mature more frequently.
For life and annuity businesses, she said the situation was more complex because their obligations generally extend over longer periods.
According to her, existing long-duration fixed-income investments could benefit from falling market yields, but insurers would also face higher values for some long-term liabilities, while new premiums and maturing investments would have to be deployed at lower prevailing rates.
She consequently stressed the importance of effective asset-liability management, particularly for life insurers.
Nwachukwu also rejected the characterisation of insurers’ investments in government securities and other fixed-income assets as a “comfort zone” or a form of passive investment.
She explained that insurers manage policyholders’ funds and are required to preserve capital, maintain liquidity and ensure that their assets are appropriately matched with their liabilities.
However, she said the more significant structural consequence of a sustained lower-yield environment would be reduced scope for insurers to depend on investment returns to offset poor underwriting results.
She maintained that investment income should support a sound insurance business rather than permanently compensate for inadequate pricing or underwriting losses.
The NIA chairman said insurers should therefore place greater emphasis on technical underwriting performance, appropriate pricing and operational efficiency as the industry adjusts to changing interest-rate conditions.
At the same time, she said the rate cut could create opportunities for the insurance industry if lower borrowing costs translate into increased economic activity.
According to her, improved access to credit could encourage investment in sectors such as manufacturing, infrastructure, construction and trade, while also increasing demand for vehicles, machinery and other assets that require insurance protection.
She said the resulting expansion in economic activity could enlarge the pool of risks available to insurers and create opportunities for premium growth.
Nwachukwu, however, cautioned insurers against treating rising premium volumes as the only measure of business success.
She said growth would be meaningful only where increased premiums generate sustainable returns after accounting for claims, acquisition expenses and other operating costs.
The NIA chairman noted that an insurer could record significant premium growth without creating value if claims and expenses increased at a faster pace.
She said the industry therefore needed to prepare for an operating environment where the quality of underwriting, pricing discipline and cost management would have a more pronounced effect on insurers’ financial performance.
The development comes as insurers continue to adjust their business strategies amid changes in monetary conditions and efforts to strengthen the sector’s financial sustainability.
For Nwachukwu, the rate-cut environment should prompt insurers to balance investment management with stronger underwriting discipline while positioning themselves to capture new risks that may emerge from increased economic activity.