Nigeria’s insurance industry could be approaching a major turning point, as industry leaders, technology entrepreneurs and investors explore how digital innovation and stronger funding could transform the way Nigerians access insurance.
The conversation will take centre stage at the fifth edition of Insurance Meets Tech (IMT), scheduled for November 20, 2026, in Lagos. The event will examine what it would take to build Nigeria’s first insurance unicorn—a privately held company valued at $1 billion or more.
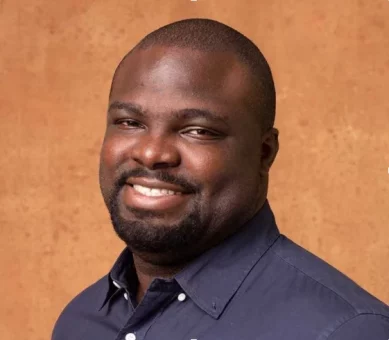
At the centre of the discussion is Iyinoluwa Aboyeji, co-founder of Andela and Flutterwave and a founding partner of investment firm Future Africa. He is expected to deliver a presentation titled Capital, Code and the Race to Nigeria’s First Insurance Unicorn.
His participation highlights a growing question for the industry: could the combination of technology, investment and innovative insurance products unlock a market that has struggled to reach a large proportion of Nigeria’s population?
Why Is Everyone Talking About Nigeria’s First Insurance Unicorn?
Nigeria has produced technology companies that have attracted international investment and achieved billion-dollar valuations. However, the insurance sector has yet to produce a comparable success story.
According to the event organisers, Aboyeji’s experience building technology businesses and supporting emerging entrepreneurs makes him a fitting speaker for discussions about the industry’s future.
The conference, themed Building Insurance That Connects, will explore how insurers can use technology to reach customers through digital platforms they already use.
The objective extends beyond creating a billion-dollar company. A successful transformation could also involve making insurance easier to understand, purchase and access, particularly for individuals and businesses that have traditionally remained outside the formal insurance market.
However, becoming an insurance unicorn would require more than a popular application or a large customer base. Sustainable growth would depend on customer trust, sound underwriting, regulatory compliance, effective claims management and a business model capable of generating long-term value.
How Technology Could Make Insurance More Accessible to Nigerians
For many Nigerians, purchasing insurance can seem complicated. Customers may struggle to understand policy terms, identify suitable products or determine how to initiate a claim.
Technology offers opportunities to address some of these challenges.
Digital insurance platforms could allow customers to compare policies, obtain quotations, purchase coverage and manage their policies using mobile phones.
Insurers could also integrate insurance products into existing payment applications, online marketplaces, banking platforms and other digital services.
For example, a small business owner using a digital payment platform might be offered suitable business protection. A driver could access motor insurance through a digital service, while a farmer might obtain agricultural coverage through a platform already used to manage farming activities.
Such arrangements could reduce the effort required to purchase insurance and bring products closer to potential customers.
Technology could also improve communication between insurers and policyholders, provide faster access to policy documents and make it easier to track claims.
Nevertheless, digital convenience alone will not solve every problem. Customers must still understand what they are buying, what their policies exclude and the conditions they must satisfy before receiving compensation.
The Funding Question: Can More Capital Transform the Insurance Industry?
Capital is another important part of the discussion.
Insurance companies need sufficient financial resources to meet their obligations, develop products, invest in technology and expand their operations.
The Insurance Meets Tech conference comes amid changes to Nigeria’s insurance regulatory and operating environment, including the Nigerian Insurance Industry Reform Act and the sector’s recapitalisation exercise.
These developments have increased attention on the financial strength and long-term competitiveness of insurance companies.
Stronger capital bases could create opportunities for insurers to invest in digital infrastructure, improve service delivery, develop new distribution channels and explore partnerships with technology companies.
However, additional capital does not automatically translate into wider insurance adoption.
For investment to produce meaningful results, insurers must develop products that address real customer needs, price risks appropriately and maintain the financial discipline required to pay valid claims.
The challenge will be converting financial resources into practical benefits for policyholders.
Why Millions of Nigerians Still Need Better Insurance Access
One of the industry’s most significant opportunities lies in expanding coverage among individuals and businesses that have limited access to formal insurance.
Low awareness, affordability concerns, distrust and difficulties understanding policy conditions can discourage people from purchasing insurance.
For lower-income households, even a relatively modest premium may compete with essential expenses such as food, housing, transportation and education.
Small businesses face similar challenges. Many operate with limited reserves and may struggle to recover from fires, accidents, property damage or other unexpected events.
Technology-enabled insurance could help address some of these barriers through simpler purchasing processes, flexible payment arrangements and products tailored to specific occupations or risks.
Group insurance distributed through cooperatives and professional associations could also provide another route to wider coverage.
For such initiatives to succeed, however, insurers must ensure that products remain affordable without compromising adequate coverage, transparent terms or the ability to meet claims obligations.
What Could an Insurance Technology Boom Mean for Consumers?
If insurers successfully combine digital innovation with customer-focused products, consumers could benefit in several ways.
Easier access to insurance: Digital platforms could reduce the time and effort required to obtain coverage.
More relevant products: Data and technology could help insurers develop products suited to particular customer groups, occupations and financial circumstances.
Improved customer service: Digital policy management and claims-tracking systems could make it easier for customers to obtain information about their coverage and claims.
Wider financial protection: Better distribution channels could help insurance reach people who have traditionally been underserved.
Greater competition: New technology-driven businesses could encourage established insurers to improve their products, pricing transparency and service delivery.
These benefits are possibilities rather than guaranteed outcomes. Their realisation will depend on implementation, effective regulation, consumer protection and the quality of the products being offered.
Customers should also remain alert to cybersecurity risks, data privacy concerns and misleading marketing claims as more insurance services move online.
Can Nigeria Produce a Billion-Dollar Insurance Company?
The possibility of Nigeria producing its first insurance unicorn raises important questions about the industry’s business models and growth prospects.
A technology-driven insurer or insurance distribution platform would need to solve a significant customer problem, build a trusted brand and develop an operation that can expand sustainably.
It would also need to navigate insurance regulation, manage risk responsibly and demonstrate that its products deliver genuine value.
Distribution may prove particularly important. Instead of relying exclusively on traditional sales channels, businesses could reach customers through digital partnerships, mobile services and other platforms that already attract large audiences.
But scale must be accompanied by quality. Rapid customer acquisition will mean little if policyholders struggle to understand their coverage or receive valid claims payments.
The industry’s long-term success will therefore depend on balancing innovation with sound insurance practices.
Insurance Meets Tech 2026: What to Expect
The fifth edition of Insurance Meets Tech is scheduled for November 20, 2026, in Lagos.
According to the organisers, the event will bring together industry executives, technology founders, investors, regulators and policymakers to discuss how capital and technology can support insurance growth.
Aboyeji’s presentation will focus on the relationship between investment, technology and the ambition to establish Nigeria’s first insurance unicorn.
IMT convener Odion Aleobua said the industry needed to translate recent developments into stronger growth and wider adoption.
The conference is expected to provide a platform for discussing how insurers can build products that fit more naturally into the everyday financial activities of Nigerians.
Whether the discussions lead to new partnerships, investment opportunities or innovative business models, the central challenge remains the same: making insurance more accessible, relevant and trusted.
Final Thoughts: The Real Prize Is Bigger Than a Billion-Dollar Valuation
Nigeria’s ambition to produce its first insurance unicorn reflects the potential for technology and investment to reshape a sector that remains important to household financial security and business resilience.
Yet the most meaningful measure of success may not be a company’s valuation alone.
It will also be whether more Nigerians can obtain appropriate insurance, understand their policies and trust that valid claims will be handled fairly and efficiently.
If technology companies, established insurers and investors can work together to address these needs, the industry could unlock new opportunities for growth while strengthening financial protection across the country.
The big question is no longer simply whether Nigeria can build a billion-dollar insurance company. It is whether innovation can make insurance accessible to the millions of Nigerians who need it most.