NAICOM Reveals What Nigeria’s Insurance Industry Must Do to Win Public Trust
Nigeria’s insurance industry has received a fresh challenge from its regulator: rebuild public confidence, make insurance more accessible and play a greater role in financing the country’s economic development.
The National Insurance Commission (NAICOM) has called on insurance brokers to raise professional standards, improve service delivery and help expand insurance coverage across the country.
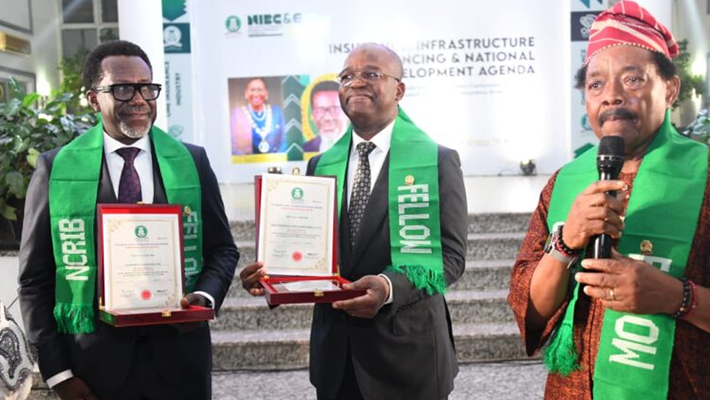
The Commissioner for Insurance and Chief Executive Officer of NAICOM, Olusegun Omosehin, made the call at the 2026 National Insurance Brokers Conference and Exhibition in Abuja.
Held under the theme “Insurance: Infrastructure Financing & National Development Agenda,” the conference focused on how the insurance sector could contribute more meaningfully to Nigeria’s economic growth.
The message was clear: the industry’s long-term growth depends not only on financial strength but also on public confidence, accountability and the value customers receive.
Why NAICOM Wants Insurance Brokers to Rebuild Public Confidence
Insurance brokers occupy an important position between customers and insurance companies. They help clients assess risks, select appropriate policies and navigate insurance arrangements.
According to Omosehin, brokers must strengthen their role in risk management, consumer protection and investment mobilisation.
For customers, trust is essential when purchasing insurance. Policyholders need to understand what their policies cover, what exclusions apply, how premiums are calculated and what steps to take when making claims.
When customers find insurance products difficult to understand or have concerns about service delivery, they may be reluctant to purchase cover or renew existing policies.
This makes transparent communication, professional conduct and reliable customer service important priorities for brokers seeking to improve the industry’s reputation.
Rebuilding confidence, however, requires cooperation across the insurance value chain. Brokers, insurers and regulators all have responsibilities in ensuring that customers receive clear information and that legitimate claims are handled in accordance with policy terms.
NIIRA 2025: What the Insurance Reform Means for the Industry
The NAICOM chief also highlighted the Nigerian Insurance Industry Reform Act (NIIRA) 2025 as a framework for strengthening the sector.
According to him, the legislation is intended to support greater financial capacity, improved corporate governance and stronger accountability within the industry.
These priorities are significant because a resilient insurance sector needs institutions capable of managing risks, meeting their contractual obligations and maintaining sound business practices.
For insurance companies, regulatory reforms can also increase the importance of capital planning, compliance and operational efficiency.
For customers, the broader objective is an industry that operates transparently and provides greater confidence in the protection it sells.
However, the practical impact of any reform will depend on its implementation, regulatory oversight and how insurance companies and intermediaries respond to their obligations.
Digital Technology Could Make Insurance More Accessible
Omosehin urged brokers to embrace innovation and digital technologies while maintaining compliance with regulatory requirements.
Technology could help brokers reach customers who have traditionally found insurance difficult to access. Digital platforms may also make it easier to compare products, obtain quotations, communicate with providers and manage policy information.
For example, online services can help customers initiate policy enquiries without visiting a physical office. Digital communication tools can also support reminders, document submission and updates during the claims process.
But digitalisation alone will not guarantee greater public confidence.
Customers must still be able to understand the products they purchase, access assistance when problems arise and receive appropriate protection under their policy terms.
Insurance businesses therefore need to combine technological improvements with professional advice, clear documentation, data protection and responsive customer support.
How Insurance Can Help Finance Nigeria’s Infrastructure
Another key message from the conference was the potential for insurance to contribute to infrastructure financing and national development.
Insurance companies collect premiums in exchange for providing protection against specified risks. Their investment activities can also provide a channel through which funds are allocated to financial assets and other eligible investment opportunities.
With suitable regulation, prudent investment management and appropriate risk controls, the insurance industry can help mobilise long-term capital that supports economic activity.
Infrastructure development may create opportunities for insurers and brokers in areas such as construction insurance, engineering risks, property protection, marine insurance and other forms of commercial cover.
Brokers can help businesses and project owners identify exposures and arrange suitable insurance protection. This can support better risk management for projects involving substantial capital expenditure.
Nevertheless, insurance funds cannot be directed indiscriminately into infrastructure projects. Investment decisions must account for regulatory requirements, liquidity needs, policyholder obligations and the risks associated with individual investments.
The sector’s contribution will therefore depend on sound financial management and the availability of appropriate investment opportunities.
Strategic Partnerships Could Expand Insurance Coverage
NAICOM also called on brokers to establish strategic partnerships with other sectors of the economy.
Collaboration with businesses, financial institutions and technology providers could help make insurance products available through channels customers already use.
For example, insurance may be offered alongside certain banking services, commercial transactions or business financing arrangements where appropriate.
Such partnerships could help insurers and brokers reach more individuals and businesses while developing products that respond to specific risks.
Small businesses, property owners, transport operators and other commercial customers may benefit from access to professional advice and suitable risk protection.
However, expanding distribution must go hand in hand with consumer education. Customers should understand whether a product is compulsory or optional, the risks it covers, the premium payable and the circumstances under which claims may be rejected.
The objective should be to expand meaningful insurance protection, rather than simply increase the number of policies sold.
What This Means for Nigerians Buying Insurance
For individuals and businesses, the regulator’s message reinforces the importance of transparency and professional service in the insurance market.
Consumers can take practical steps to protect their interests when purchasing a policy:
- Verify the provider: Check the insurer’s or intermediary’s authorisation and regulatory status through appropriate official channels.
- Understand the cover: Ask what risks are covered and which exclusions or conditions apply.
- Review the premium: Confirm the amount payable, payment arrangements and any additional charges.
- Keep documentation: Retain policy documents, receipts and relevant communications.
- Understand the claims process: Ask what documents are required, how to report a loss and how claims are assessed.
- Ask questions before signing: Seek clarification about any term or condition that is unclear.
These measures can help customers make informed decisions and understand their rights and responsibilities under an insurance contract.
A more trusted insurance market requires informed customers as well as responsible insurers and brokers.
NAICOM Wants Conference Resolutions to Produce Real Results
Omosehin challenged participants at the conference to turn their discussions and resolutions into measurable actions that would improve insurance penetration, support infrastructure financing and contribute to national development.
That challenge places responsibility on industry stakeholders to move beyond promises and focus on practical improvements.
Progress could be reflected in clearer customer communication, stronger professional standards, better use of technology, improved access to appropriate products and more effective risk management.
The regulator also reiterated its commitment to a stronger, more transparent and customer-focused insurance sector.
For the industry, the challenge is to demonstrate that these commitments translate into meaningful improvements for policyholders and businesses.
Conclusion: Trust Could Be the Key to Nigeria’s Insurance Growth
NAICOM’s call to insurance brokers highlights three priorities for the future of Nigeria’s insurance industry: public confidence, technological innovation and a greater contribution to economic development.
The regulator believes brokers can help achieve these goals by improving professional standards, protecting consumers, building strategic partnerships and making insurance more accessible.
The NIIRA 2025 framework is also expected to support efforts to strengthen the industry’s financial capacity, governance and accountability.
Ultimately, the industry’s credibility will depend on more than regulatory announcements and conference resolutions. Customers need understandable policies, professional advice, transparent processes and claims handled in line with contractual obligations.
If Nigeria’s insurance industry can translate these priorities into consistent results, it could strengthen public confidence while expanding its contribution to businesses, infrastructure and the wider economy.