Senator Abiru Honoured for His Role in Nigeria’s Insurance Reforms
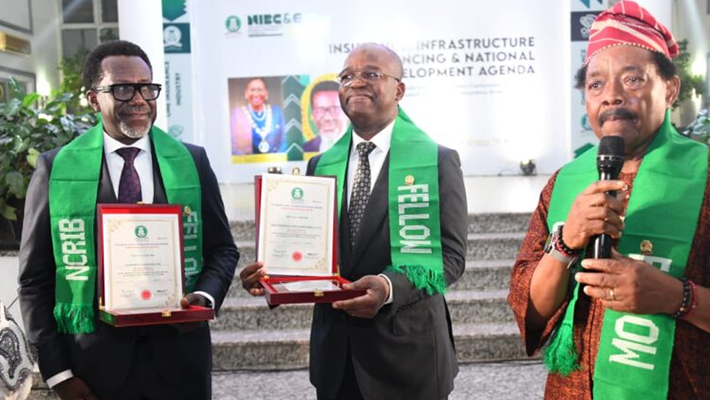
Nigeria’s insurance industry reforms have received renewed attention following the conferment of an honorary fellowship on Senator Mukhail Abiru by the Nigerian Council of Registered Insurance Brokers (NCRIB).
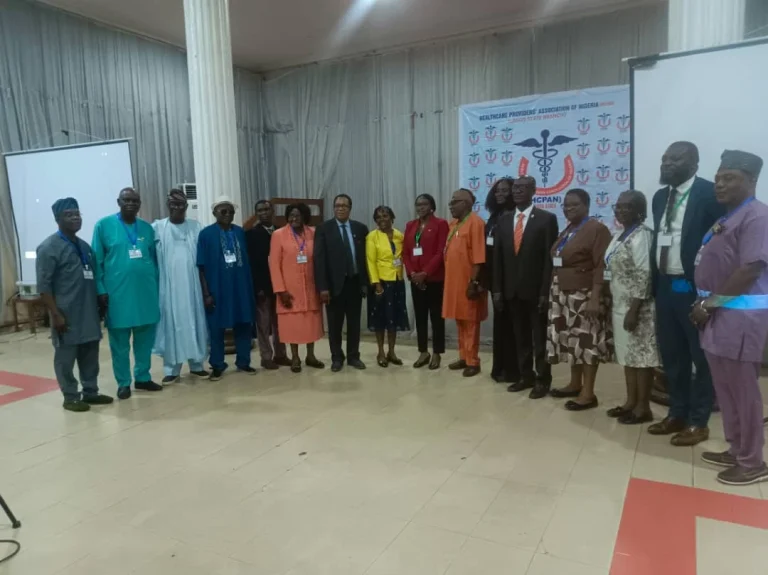
Abiru, who chairs the Senate Committee on Banking, Insurance and Other Financial Institutions, received the honour at the council’s 2026 Closing Dinner of the National Insurance Conference and Exhibition in Abuja on Wednesday.
According to a statement by his spokesman, Enitan Olukotun, the fellowship recognises Abiru’s contributions to insurance sector reforms, engagement with industry stakeholders and involvement in the passage of the Nigeria Insurance Industry Reform Act (NIIRA) 2025.
The recognition comes as Nigeria’s insurance industry undergoes significant regulatory and capital changes intended to strengthen its capacity and improve its contribution to the economy.
For insurance companies, brokers and policyholders, the bigger question is whether these reforms will translate into stronger institutions, better customer service and wider access to insurance protection.
NIIRA 2025: The Law at the Centre of Industry Reform
One of the major developments highlighted during the ceremony was the passage of the Nigeria Insurance Industry Reform Act 2025.
Abiru sponsored the proposed legislation, which President Bola Tinubu assented to on July 31, 2025.
In his goodwill message, the senator described the fellowship as recognition not only of his personal efforts but also of the collective work of the National Assembly, the executive, regulators and insurance industry stakeholders.
He said the sector had historically faced challenges, including low insurance penetration, limited public awareness and concerns about consumer confidence.
These challenges have made strengthening the industry an important priority for regulators and policymakers.
A well-functioning insurance market can help households and businesses manage financial risks, protect assets and recover from covered losses. However, achieving these outcomes requires more than legislation: insurers must operate responsibly, customers must understand available products, and claims must be handled in accordance with policy terms.
The long-term significance of NIIRA will therefore depend on implementation, regulatory oversight and how effectively industry participants meet their obligations.
Recapitalisation: 43 Insurance and Reinsurance Companies Reportedly Meet New Capital Requirements
Abiru also pointed to progress in the industry’s recapitalisation programme.
According to his remarks, the National Insurance Commission (NAICOM) reported in August 2026 that 43 insurance and reinsurance companies had met the new minimum capital requirements.
Recapitalisation is intended to strengthen insurers’ financial capacity and improve their ability to manage the risks associated with their businesses.
For insurance companies, adequate capital is important because claims obligations and other liabilities can create substantial financial demands, particularly when significant losses occur.
Stronger capital positions may also improve insurers’ capacity to pursue suitable business opportunities, subject to regulatory requirements and prudent risk management.
However, meeting a minimum capital requirement does not automatically guarantee that an insurer will provide excellent customer service, settle every claim immediately or achieve higher profitability.
Consumers should continue to consider an insurer’s reputation, policy terms, financial disclosures and claims-handling practices when choosing coverage.
Editorial note: The figure of 43 companies is attributed to the report cited in Abiru’s remarks and should be checked against the relevant NAICOM announcement before publication.
New Regulatory Bill Could Reshape Insurance Supervision
The senator also highlighted the proposed Insurance Regulatory Commission Bill 2026, which he said seeks to modernise the regulatory framework and strengthen supervisory and enforcement capacity.
The proposal was presented as an effort to improve the institutional capacity required to implement and enforce insurance regulations.
Effective supervision matters because insurers handle funds intended to provide protection against future losses. Regulators need appropriate powers and systems to monitor compliance, identify risks and respond to misconduct or financial weaknesses.
However, the bill remains a proposal according to the source report. Its legal status and provisions should be confirmed before any claims are made about the changes it would introduce or when they might take effect.
For insurers and brokers, developments in regulatory policy are worth monitoring because changes to supervisory requirements can affect compliance procedures, governance and business operations.
Why Public Trust Remains a Major Challenge
Despite the reforms, Abiru acknowledged that low insurance penetration, limited public awareness and concerns about consumer confidence remain important challenges for the industry.
Public trust is crucial to insurance adoption. Customers need confidence that they understand what they are purchasing and that their insurers will honour valid claims under the terms of their policies.
When insurance products are poorly explained or customers encounter difficulties during the claims process, confidence can suffer.
Improving trust requires coordinated action from insurers, brokers and regulators.
Important priorities include:
- Clear policy information: Customers should understand the coverage, exclusions, premiums and conditions attached to their policies.
- Professional brokerage services: Brokers should provide appropriate guidance and act transparently when helping clients select insurance products.
- Reliable claims handling: Insurers should assess and pay valid claims in accordance with contractual terms and applicable regulations.
- Consumer education: Industry stakeholders should explain the benefits and limitations of different forms of insurance.
- Accountability: Complaints and compliance concerns should be addressed through effective procedures and regulatory oversight.
- Innovation: Digital tools can improve access to information, purchasing processes and customer support when implemented responsibly.
These measures can help make insurance easier to understand and more useful to households and businesses.
How Stronger Insurance Companies Could Support Nigeria’s Economy
Abiru said a stronger insurance industry would be better positioned to support businesses, infrastructure and investment while improving economic resilience.
Insurance contributes to economic activity by helping individuals and organisations manage specified financial risks. Businesses with appropriate insurance protection may be better placed to recover from covered events, while households can reduce exposure to certain unexpected losses.
The sector can also contribute to investment markets through the management of funds, subject to applicable investment rules, liquidity requirements and policyholder obligations.
For example, businesses operating in construction, manufacturing, transportation and other capital-intensive sectors may require insurance to manage risks associated with their operations and assets.
An insurance market with stronger financial capacity and effective regulation could support these needs more reliably.
Nevertheless, the industry’s broader economic contribution will depend on responsible underwriting, sound investments, effective claims management and greater access to suitable products.
What the NCRIB Fellowship Means for Insurance Brokers
The NCRIB’s decision to honour Abiru also draws attention to the role of insurance brokers in the sector’s development.
Brokers help individuals and organisations assess risks, understand insurance options and arrange coverage with insurers. They can also assist clients in navigating policy requirements and claims-related processes.
Abiru urged insurance professionals and brokers to maintain high standards of professionalism, transparency, innovation and customer service.
For brokers, these priorities are particularly relevant as regulatory changes and recapitalisation reshape the operating environment.
Brokers who communicate clearly, understand their clients’ needs and maintain professional standards can help customers make more informed decisions.
Their role may become even more important as the industry seeks to expand coverage among individuals and businesses that have limited experience with formal insurance products.
What Should Policyholders and Insurance Customers Watch Next?
For the public, the most meaningful measure of insurance reform will be whether it improves the protection customers can actually access.
Rather than judging progress solely by awards, legislation or recapitalisation figures, consumers can watch for practical developments such as:
- More accessible and understandable insurance products.
- Clearer communication about policy benefits and exclusions.
- Better customer support and claims processes.
- Stronger regulatory oversight and accountability.
- More insurance options for households, small businesses and other underserved groups.
These outcomes are not guaranteed by reform announcements alone. They require consistent implementation and responsible conduct across the industry.
Conclusion: Can Nigeria’s Insurance Reforms Deliver Lasting Change?
Senator Mukhail Abiru’s honorary fellowship from the NCRIB recognises his reported contributions to Nigeria’s insurance reform agenda, including his role in the passage of NIIRA 2025.
His remarks also highlight the sector’s continuing priorities: stronger capital positions, effective regulation, greater public awareness and improved consumer confidence.
The reported progress in recapitalisation and the proposed regulatory bill signal developments that industry stakeholders will be watching closely.
Ultimately, the success of these initiatives will be measured by their practical effects on insurers, brokers, businesses and policyholders.
Nigeria’s insurance industry has an opportunity to strengthen its role in the economy—but lasting progress will depend on effective regulation, professional service and public confidence built through results.