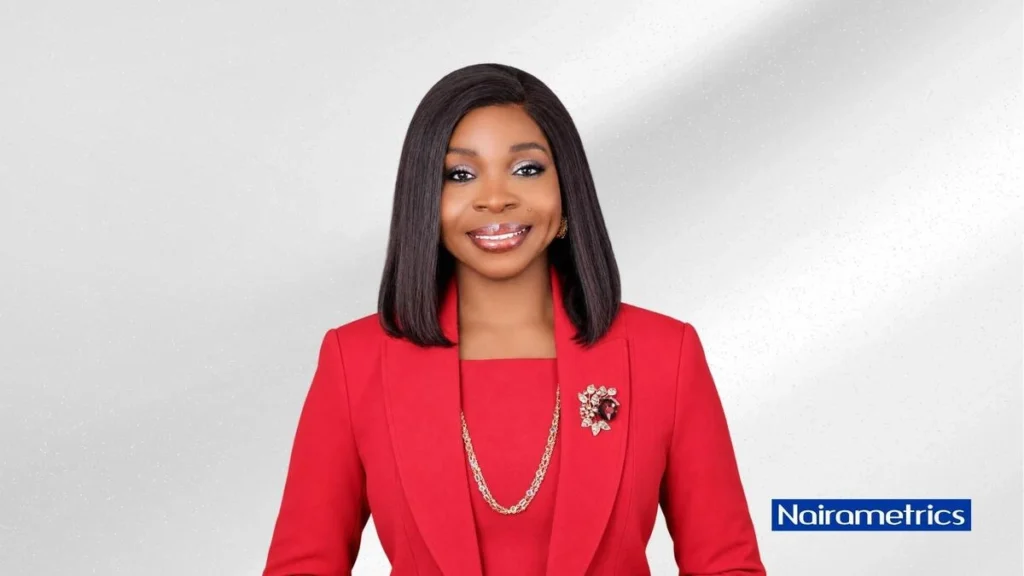
Nigeria’s insurance industry must look beyond recapitalisation and focus on rebuilding public trust, investing in technology and developing products that address consumers’ needs if it is to achieve meaningful growth, Consolidated Hallmark Insurance (C.H.I) Managing Director and Chief Executive Officer, Mary Adeyanju, has said.
Adeyanju said the recently concluded recapitalisation exercise, which raised about N700 billion across the industry, would strengthen insurers’ capacity to retain more business and pursue expansion, but would not by itself resolve the sector’s long-standing credibility problem.
Her comments come against the backdrop of the insurance industry’s relatively small contribution to Nigeria’s economy despite the country’s large population and significant business activity.
Data from the National Bureau of Statistics showed that financial institutions accounted for 87.22% of the finance and insurance sector’s output in the second quarter of 2026, while insurance contributed 12.78%.
In real terms, the broader finance and insurance sector accounted for 3.37% of GDP during the period, with insurance contributing less than 1%.
Adeyanju identified public distrust as one of the biggest obstacles to wider insurance adoption, saying negative experiences with insurers have helped create a perception that insurance is difficult to access or unreliable when claims arise.
According to her, the industry needs to demonstrate its value more effectively, particularly to individuals and small businesses that may lack the financial capacity to recover from unexpected losses.
She said C.H.I was therefore working on products tailored to the needs of customers rather than simply marketing existing offerings.
“We’re looking at SME products, little products that we can sell that will get across to those people,” she said.
The insurer is also exploring partnerships and alternative distribution channels, including bancassurance and other intermediaries, to make insurance products more accessible without relying solely on traditional sales methods.
Adeyanju said technology would form another major part of the industry’s transformation, arguing that insurers must become increasingly technology-driven to remain competitive.
Technology as a catalyst
She expects insurers to channel part of the capital raised during the recapitalisation exercise into digital infrastructure, operational efficiency and customer service.
Adeyanju pointed to C.H.I’s use of Curacel for motor insurance claims as an example of how technology can shorten the claims process.
The system allows customers to carry out vehicle inspections and submit photographs and other information digitally. The insurer can then process the claim remotely, determine repair costs and make an offer based on updated market information.
Such systems, she said, could reduce delays and improve customers’ experience at one of the most important points in the insurance relationship — when a claim is made.
For Adeyanju, improving claims turnaround is particularly important because customers often do not experience the tangible benefit of insurance until they suffer a loss.
“Insurance is the product that not just Nigerians, but everybody in the world needs,” she said, adding that the industry must do more to communicate its value to consumers.
Capital to boost capacity and jobs
While she acknowledged that trust remains unresolved, Adeyanju said recapitalisation had addressed another major industry challenge: capacity.
With stronger balance sheets, insurers should be able to retain a greater proportion of risks within Nigeria and pursue larger opportunities.
She also expects the additional capital to support investment in human resources.
Adeyanju said the industry has struggled to attract top talent partly because insurance professionals are generally paid less than their counterparts elsewhere in the financial services sector.
Greater investment in people and technology, she argued, could improve efficiency while also creating additional employment opportunities as insurers expand their operations.
C.H.I profit surge largely investment-driven
Adeyanju also attributed Consolidated Hallmark Holdings Plc’s sharp increase in profit before tax during the first half of 2026 largely to gains from its investments in the capital market.
The group reported N27.10 billion in profit before tax for the six months ended June 30, 2026, compared with N1.76 billion in the corresponding period of 2025.
Adeyanju said approximately 80% of the increase was attributable to fair-value gains from investments, particularly equities that appreciated significantly during the period.
She stressed, however, that the underlying insurance business remained profitable.
The company had experienced some slowdown during the recapitalisation period as customers reduced or delayed transactions while waiting to see which insurers would meet the new capital requirements.
Adeyanju described the period as one of recovery, with the company now focused on rebuilding operational earnings.
Investor confidence improves
The C.H.I chief executive also linked the rise in the company’s share price over the past year to improving investor sentiment toward the insurance sector.
She said the successful recapitalisation exercise had demonstrated that investors were increasingly willing to commit funds to insurance businesses where they see potential for attractive returns.
C.H.I’s evolution into a holding company has also strengthened the group’s proposition, she said.
The business has expanded beyond its original general insurance operations into areas including finance, health maintenance and life insurance, creating a broader group structure.
According to Adeyanju, that diversification has helped reinforce confidence in the company’s long-term prospects.
C.H.I did not need fresh capital
Unlike many insurers that raised funds during the recapitalisation exercise, C.H.I did not need to issue new capital to meet the requirement.
Adeyanju said the group already had sufficient resources to satisfy the applicable capital threshold.
She said the company had N32 billion as of December 31, 2025, against a requirement of N15 billion for its general insurance business.
Its life insurance subsidiary, in which C.H.I owns a 98.2% stake, also had N10.2 billion at the time, slightly above the N10 billion requirement.
For the company, she said, the more important question is now how to deploy its capital effectively and generate greater value from it.
Life portfolio acquisition expands reach
Adeyanju also confirmed that C.H.I’s life insurance subsidiary had completed the acquisition of NSIA Insurance’s life portfolio after obtaining approval in principle from the National Insurance Commission (NAICOM).
She described the transaction as one of the opportunities created by the recapitalisation process.
Some insurers, she explained, may decide to concentrate resources on a particular line of business rather than maintain operations across both general and life insurance.
For C.H.I’s life business, the acquisition provides an opportunity to gain immediate access to customers and premium income rather than building a portfolio entirely from scratch.
Adeyanju said the transaction illustrates how stronger capital positions can enable insurers to take advantage of opportunities emerging as the industry restructures.
Ultimately, however, she maintained that the industry’s ability to translate its new capital base into sustainable growth will depend on more than financial strength.
Insurers will need to improve customer experience, embrace technology, attract skilled professionals and, above all, convince Nigerians that insurance delivers value when they need it most.