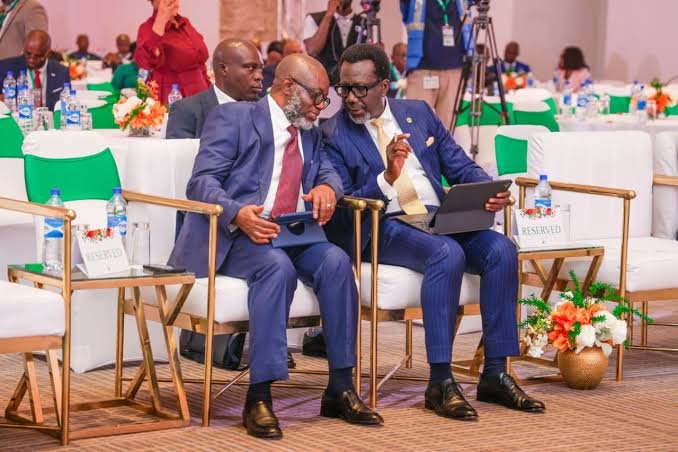
The National Insurance Commission (NAICOM) has warned insurance companies that raising their capital does not automatically guarantee financial stability, urging their directors to strengthen corporate governance, risk management and accountability.
The Commissioner for Insurance and Chief Executive Officer of NAICOM, Olusegun Omosehin, gave the warning at the 8th Annual Insurance Directors’ Conference in Lagos.
Speaking on the theme, “Recapitalisation to Resilience: Leading the Risk-Based Capital (RBC) Era,” Omosehin said the success of the ongoing industry transformation would depend not simply on how much capital insurers raise, but on how effectively they manage and deploy the funds.
He challenged insurance companies to move beyond meeting regulatory capital requirements and focus on building financially sound, transparent and well-governed institutions.
According to him, recapitalisation should be viewed as the beginning of a more demanding phase for the industry, where companies must demonstrate that their capital is properly protected, invested and matched with the risks they undertake.
“Recapitalisation is never the destination; it is the gateway to a more demanding phase; a phase that will be defined not by the size of capital alone, but by how that capital is governed, protected, deployed and aligned with risk,” he said.
Why Well-Capitalised Insurance Companies Can Still Fail
Omosehin warned that having substantial financial resources does not necessarily make an insurance company resilient.
He identified poor corporate governance, weak internal controls, ineffective risk management, inappropriate investments and inadequate board supervision as factors that could undermine even well-capitalised institutions.
The NAICOM chief said directors must take greater responsibility for the performance and stability of their companies rather than limiting their roles to attending board meetings or protecting shareholders’ interests.
He urged board members to scrutinise management decisions, assess business strategies and ensure that companies operate within their financial capacity and approved risk limits.
He also warned insurers against losing their newly raised capital through poor underwriting decisions, excessive operating expenses, risky investments and uncontrolled business expansion.
According to him, boards must pay closer attention to risks associated with claims, reinsurance arrangements, investments, liquidity, technology and daily operations.
NAICOM Demands Better Claims Settlement, Transparency
The commissioner said changing technology, consumer expectations and emerging risks were reshaping the insurance industry, making it necessary for companies to improve their services and develop products that address customers’ needs.
He noted that policyholders increasingly expect transparency, faster service, affordable insurance products and efficient digital platforms.
However, he stressed that customers’ most important expectation was the assurance that genuine claims would be paid when due.
Omosehin said NAICOM would pay closer attention to the quality of insurers’ capital, financial reporting, risk management systems and ability to meet their obligations.
He also directed insurance companies to provide accurate and timely financial information to the regulator while strengthening their internal audit, compliance and risk management departments.
The commissioner further emphasised that directors and senior executives must be appointed based on competence, experience, integrity and professional ability rather than personal relationships or influence.
He said board members should possess relevant knowledge of insurance, finance, law, investments, technology and risk management to effectively supervise increasingly complex businesses.
Shareholders’ Interests Must Not Override Policyholders’ Protection
Omosehin cautioned that the pursuit of shareholders’ returns must not encourage insurance companies to take excessive risks or pursue unsustainable expansion at the expense of policyholders.
He said the recapitalisation exercise should produce measurable improvements in underwriting capacity, claims settlement, customer service and public confidence.
According to him, a stronger insurance industry could play a bigger role in financing critical sectors of the Nigerian economy, including infrastructure, energy, manufacturing and agriculture.
He explained that increased financial capacity could help local insurers retain more risks within Nigeria, reduce dependence on foreign insurance markets, attract long-term investments and extend insurance coverage to more people and businesses.
However, he maintained that these benefits would only materialise if companies also embraced stronger governance, innovation and prompt settlement of genuine claims.
“The public does not measure the strength of an insurance company by the size of its capital alone. Ultimately, policyholders judge institutions by their willingness and ability to honour their contractual obligations,” he said.
Omosehin described claims settlement as one of the most important factors influencing public confidence in the insurance industry, urging directors to make policyholder protection central to their corporate strategies.
He added that decisions taken by insurance company boards would determine whether recapitalisation delivers lasting improvements in the industry’s financial strength, competitiveness and reputation.