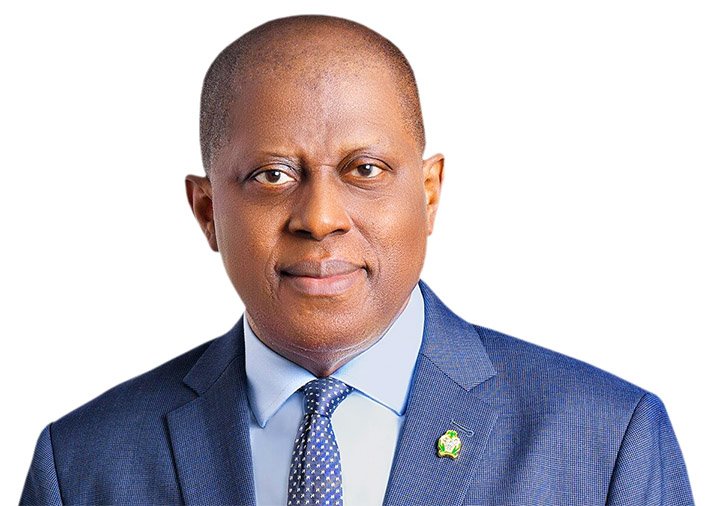
Central Bank of Nigeria (CBN) Governor, Olayemi Cardoso, has identified price stability as a critical requirement for deepening financial inclusion, warning that persistent inflation and exchange-rate volatility could undermine progress in access to formal financial services.
Cardoso spoke in Abuja at the launch of the Access to Financial Services in Nigeria (A2F) 2026 Survey Report, where he said economic instability weakens household purchasing power, discourages savings and raises the cost of credit, particularly for low-income and underserved Nigerians.
According to him, restoring price stability and confidence must therefore remain central to the financial inclusion agenda.
Represented at the event by the CBN Director of Consumer Protection and Financial Inclusion, Aisha Isa Olatinwo, Cardoso said the bank had, since 2024, refocused its operations on monetary and price stability through tighter liquidity management, improved monetary-fiscal coordination and more consistent use of monetary policy instruments.
He added that the CBN was transitioning towards an inflation-targeting framework aimed at strengthening transparency and accountability while improving policy predictability for households, businesses and investors.
“Restoring price stability and confidence is therefore not separate from financial inclusion. It is fundamental to it,” he said.
Financial Inclusion Reaches 79 Per Cent
The 2026 A2F survey showed that financial inclusion in Nigeria had risen to 79 per cent, representing about 94.2 million adults, while formal inclusion stood at 73 per cent, or approximately 87.2 million adults.
However, access to formal credit, pensions and insurance remained relatively limited.
The survey indicated that only 10 per cent of adults, representing about 12 million people, had obtained formal credit from regulated providers.
Similarly, only nine per cent, or about 11 million adults, had access to pensions, while 5.2 per cent, equivalent to 6.2 million adults, had formal insurance protection.
Digital financial services recorded wider usage, with 64.4 per cent, or approximately 77 million adults, using digital channels to receive income, make payments and remit money.
The report also showed that financial exclusion had declined to 21 per cent, although access remained uneven, particularly among poorer and vulnerable Nigerians.
Cardoso noted that previous A2F findings had also recorded substantial progress, with total financial inclusion increasing from 64 per cent in 2020 to 74 per cent, while formal inclusion rose from 56 per cent to 64 per cent.
He attributed the gains to the expansion of digital payments and agent banking, improvements in identity infrastructure, risk-based customer due diligence, financial education, regulatory innovation and collaboration among stakeholders.
The governor, however, said rural communities continued to experience higher levels of exclusion than urban areas, while regional disparities and a gender gap persisted.
He said the challenge was no longer simply to increase the number of bank accounts or financial access points, but to ensure that services were affordable, reliable, safe and capable of improving users’ financial well-being.
CBN Plans New Inclusion Framework
Cardoso disclosed that the CBN had commenced work on the fourth phase of the National Financial Inclusion Strategy following the review of the NFIS 3.0 framework.
He said the emerging strategy would move beyond broad access targets towards a more integrated, data-driven and accountable approach, with emphasis on consumer protection, digital financial safety and effective implementation at the sub-national level.
The central bank also plans to undertake geospatial mapping of financial access points to establish a national repository showing the locations of financial services, areas with persistent gaps and the performance of various payment channels.
Cardoso said the initiative would combine location, institutional, operational and transaction data to support risk-based supervision, evidence-based policymaking and targeted investment in underserved communities.
He also highlighted measures aimed at strengthening women’s access to finance, including the implementation of the Women’s Entrepreneurial Finance Code in collaboration with the Bank of Industry and the Development Bank of Nigeria.
According to him, the initiative would promote institutional accountability, gender-disaggregated data and measures to increase financing for women-owned micro, small and medium enterprises.
Identity, Agent Networks Expand
Cardoso said the infrastructure supporting financial inclusion had also expanded.
He disclosed that Bank Verification Number enrolment had reached 67.8 million by the end of 2025, representing unique Nigerians with bank accounts, while the number of bank accounts had exceeded 100 million.
He added that the agent network supported through the Shared Agent Network Expansion Facility had surpassed two million agents.
The governor also cited the Sabi Money Platform’s nationwide financial literacy programme as an initiative designed to equip Nigerians with knowledge to make informed financial decisions, avoid fraud and use financial services responsibly.
He said the CBN had redesigned and upgraded its complaints management system to provide unified complaint tracking and real-time online visibility of complaints across the banking sector.
“Assets must be accompanied by redress,” Cardoso said, stressing that consumer confidence would improve when customers were assured that their funds were protected and financial institutions could be held accountable.
Sanusi Regrets Delay in Telcos’ Entry
Also speaking at the event, the Emir of Kano and former CBN Governor, Muhammadu Sanusi II, said he regretted delaying the entry of telecommunications companies into Nigeria’s financial services sector during his tenure at the central bank.
Sanusi, who served as CBN governor from June 2009 to June 2014, said his decision had been driven largely by concerns over the safety of depositors’ funds following the banking crisis at the time.
He said subsequent developments in digital finance had demonstrated that telecommunications companies could have accelerated financial inclusion, particularly for Nigerians beyond the reach of conventional banks.
“I’m responsible for delaying the entry of telcos into this space,” Sanusi said, adding that allowing them into the sector earlier could have produced greater progress.
He nevertheless acknowledged the role of subsequent CBN administrations in opening the financial services space to telecommunications companies and fintech operators.
Banks’ Rural Footprint Remains Limited
Sanusi said the growth of digital financial services had highlighted the limitations of the traditional banking model in reaching financially excluded Nigerians.
He argued that banks lacked sufficient physical presence in many rural communities and said the expansion of digital platforms had accelerated financial inclusion in recent years.
According to him, the next stage should move beyond account opening and payments towards helping Nigerians build savings, access insurance and secure pensions.
Sanusi also urged regulators to examine the large transaction volumes processed by fintech and payment platforms and explore ways of converting part of those flows into long-term savings.
He suggested that small deductions from everyday transactions could gradually build savings pools for Nigerians who may find it difficult to make large or regular contributions.
Inclusion Must Protect Against Economic Shocks
Sanusi further argued that financial inclusion should not be measured solely by the number of accounts opened or transactions processed.
He said access to payment platforms would remain insufficient if households and businesses remained vulnerable to shocks capable of wiping out savings and investments.
He cited market fires and poor harvests as examples of events that could severely affect traders and farmers without adequate insurance protection.
The former CBN governor called for greater collaboration among the CBN, National Insurance Commission (NAICOM) and National Pension Commission (PenCom) to develop financial products combining savings, insurance and pension components, supported by existing digital infrastructure.
He also stressed the importance of financial literacy and long-term financial resilience.
“There is no enemy to savings, no enemy to wealth that is bigger than inflation,” Sanusi said, underscoring the relationship between price stability and sustainable financial inclusion.