xr:d:DAE4IBI-4Og:3371,j:40362881965,t:22110816
Nigeria’s insurance industry is entering a new phase of institutional development as regulators and operators pursue reforms aimed at strengthening financial capacity, improving consumer protection and positioning the sector to play a bigger role in economic growth.
The latest wave of reforms has largely centred on stronger capitalisation, tighter supervision, digital transformation, policyholder protection and improved market discipline.
A major milestone came with the enactment of the Nigerian Insurance Industry Reform Act 2025, which was signed into law by President Bola Ahmed Tinubu on July 31, 2025.
The legislation replaced the Insurance Act 2003 and consolidated several previous laws into a modern framework for regulating the industry.
One of the most significant provisions was the increase in minimum capital requirements for insurance operators. Life insurers moved from a N2bn minimum to N10bn, while general business operators were required to raise their capital from N3bn to N15bn. Composite insurers faced an increase from N5bn to N25bn, while reinsurers moved from N10bn to N35bn.
The 12-month recapitalisation programme, which ran from August 2025 to July 2026, subsequently produced a significant shake-up in the industry.
The National Insurance Commission disclosed that 50 insurance and reinsurance companies successfully met the new capital requirements, while six companies were left facing liquidation.
Beyond capital requirements, the regulator has also introduced measures designed to strengthen protection for policyholders.
The Insurance Policyholders’ Protection Fund was established under the new legislation, with a dedicated committee created to provide a financial safety net for customers where an insurer becomes insolvent or experiences financial distress.
The initiative also places emphasis on reducing delays in claims payments.
Technology and innovation have emerged as another major component of the industry’s reform programme. NAICOM has introduced an Insurtech licensing framework and issued its first licence in the category, while the new legislation provides for greater digitisation of insurance operations.
The regulator has simultaneously intensified enforcement of compulsory insurance requirements, including third-party motor insurance, as part of efforts to improve compliance and consumer protection.
Shift towards risk-based supervision
Following the recapitalisation exercise, NAICOM is moving towards a Risk-Based Capital framework, which is expected to align the amount of capital held by insurers with the risks associated with their individual business portfolios.
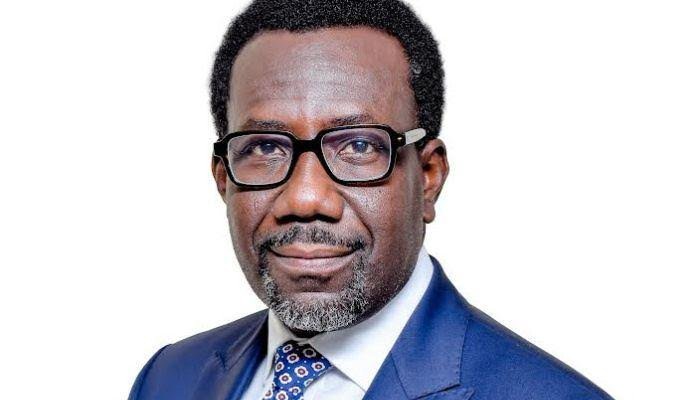
The framework is scheduled for formal unveiling at the insurers’ committee meeting on Thursday, October 8, under the chairmanship of the Commissioner for Insurance, Mr. Olusegun Ayo Omosehin.
Another notable development has been NAICOM’s willingness to intervene in distressed insurance companies where necessary to protect policyholders.
The regulator took control of African Alliance Insurance Plc in October 2024 following liquidity challenges. After an 18-month turnaround process, operational control was transferred to a new board in June 2026.
There have also been legislative proposals aimed at changing the name of NAICOM to the Insurance Regulatory Commission.
The industry’s reform agenda extends beyond Nigeria’s borders, with increased participation in regional insurance initiatives, including the ECOWAS Brown Card System.
Speaking on the broader reform programme at a BusinessDay insurance conference, Omosehin said the objective was not simply to create larger balance sheets but to build stronger institutions capable of serving policyholders more effectively.
From weak foundations to a N1.28tn market
The current reform programme builds on earlier regulatory interventions that sought to address longstanding weaknesses within the insurance market.
The enforcement of the “no premium, no cover” principle helped push the industry towards a cash-based operating model, improving insurers’ ability to manage liabilities and settle claims.
Efforts to tackle fraudulent insurance operators have also gathered pace, particularly in the motor and marine insurance segments. The Nigerian Insurers Association’s insurance database has been deployed as part of measures to identify genuine insurance policies and combat fake operators.
Microinsurance has also emerged as an important area of market development, with expectations that wider access to affordable insurance products could help improve penetration.
The industry has nevertheless travelled a difficult path. For years, weak capitalisation, limited public confidence and low demand kept insurance behind other segments of the financial services sector.
The sector’s contribution to Nigeria’s Gross Domestic Product has remained below one per cent, while consumer trust, governance concerns and low insurance penetration continue to pose challenges.
The industry also faces pressure from inflation, operational costs, regulatory fragmentation, shortages of specialised talent and the need for greater innovation.
Despite those difficulties, the market has recorded substantial growth in premium income.
The sector achieved its long-standing target of becoming a N1tn market in 2023, up from about N260bn when the Market Development and Restructuring Initiative was launched in 2009.
By the second quarter of 2026, annual premium income had risen further to N1.285tn.
Industry stakeholders believe sustaining the momentum will require reforms to go beyond capital requirements. Strong corporate governance, consumer confidence, innovation, effective regulation and wider access to insurance will remain critical to transforming the sector into a stronger contributor to Nigeria’s economic development.
As the country marks 66 years of nationhood, the insurance industry is therefore entering its next phase with a larger financial base, a more demanding regulatory environment and an expectation to translate institutional reforms into better services and greater value for policyholders.